Picture this. You land in a new country, tired and happy. You walk up to an ATM, and your card gets declined. Or worse, a surprise fee shows up days later. A bad bank choice can quietly eat 3% of every purchase.
The best bank for international travel fixes that. It keeps your money safe, your fees low, and your card working in every city. This guide explains how to pick one. It covers U.S. options, Europe, Pakistan, and fee-saving tricks. Read on, and you will pack your wallet as smartly as your suitcase.
Feature Snippet:
The best bank for international travel has no foreign transaction fees, refunds ATM charges, and offers a Visa or Mastercard that works worldwide. For U.S. travelers, Charles Schwab, Fidelity, and Capital One are popular picks. In Pakistan, Meezan Bank and UBL cards work abroad, but fees and limits differ, so confirm details first.
Best Bank for International Travel in Pakistan
The best bank for international travel in Pakistan is one that offers a Visa or Mastercard debit card with international use enabled, fair currency conversion rates, and clear limits. Meezan Bank, UBL, HBL, and Bank Alfalah are common choices. The right pick depends on your travel budget and needs.
Pakistani travelers face extra rules. The State Bank of Pakistan (SBP) sets limits on how much foreign currency people can spend abroad with cards. Because of this, the best bank is not only the one with low fees. It is also the one that explains its limits clearly.
First, ask if your card has international use turned on. Next, ask about the daily ATM limit abroad. Finally, ask how the bank converts rupees into dollars, euros, or pounds.
Travelers from the U.S. who visit family in Lahore, Karachi, or Islamabad often keep a U.S. card for fee-free spending. They also keep a small amount of rupees for local needs.
Best Bank for International Travel in Europe
For Europe, the best bank has no foreign transaction fees, refunds ATM fees, and offers a chip-and-PIN card. U.S. travelers often choose Charles Schwab Bank for debit and Capital One for credit cards. Pair one of each, and you will be covered in Paris, Rome, or Berlin.
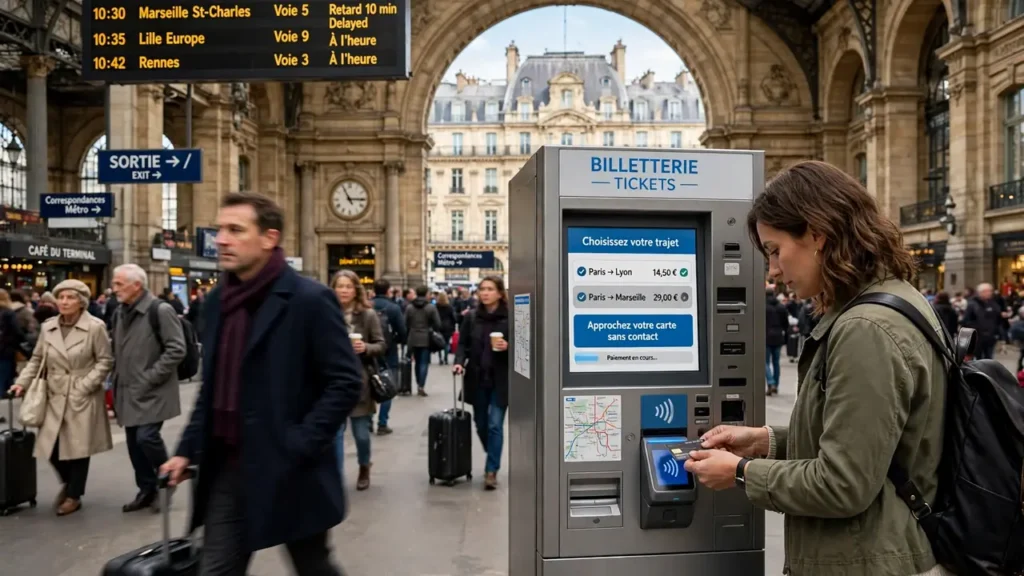
Europe loves cards. Contactless tap-to-pay is common in the UK, France, Germany, Spain, and Italy. Even small cafes accept it.
However, a few places still prefer cash. Markets, small village shops, and some public toilets may want coins. So you still need a debit card for ATMs.
Here is a simple setup for Europe:
- A no-fee credit card for hotels, trains, and restaurants
- A debit card with ATM refunds for cash
- A backup card from a different bank, kept in a separate place
Also, tell your bank about your trip. Many banks now use fraud alerts, and a travel note can prevent a surprise block.
Which Debit Card Is Best for International Transactions in Pakistan?
The best debit card for international transactions in Pakistan is a Visa or Mastercard debit card with international use enabled. Premium options like World or Platinum debit cards often add perks. Compare annual fees, foreign currency charges, and daily limits before you choose.
Many Pakistani banks offer these cards. Meezan Bank, UBL, HBL, Bank Alfalah, and others all have options. Features differ, so compare three things.
- Fees: Check the foreign currency markup and ATM charges abroadd.
- Limits: Ask about daily and yearly spending caps.
- Perks: Look for lounge access, discounts, and travel insurance.
Also, check if the card has a chip and contactless tap. Those features help in Europe and North America. Finally, read the fee schedule on the bank’s website. It is usually a free PDF.
Meezan Bank World Debit Card Benefits
MeezaBank World debitit cards typically offer international acceptance, contactless payments, and merchant discounts. Some premium cards also include lounge access or travel perks. Benefits change, so check Meezan Bank’s official website or app for the current list.
Meezan Bank is Pakistan’s largest Islamic bank. Its debit cards run on global networks like Visa and Mastercard. That means they can work at shops and ATMs worldwide.
Before you rely on any perk, do three quick checks:
- Ask if your exact card tier includes the benefit.
- Ask if lounge visits are free or limited.
- Ask if international limits apply to your account.
Perks sound great, but they only matter if you can use them. So confirm each one in writing, or screenshot it from the official page.
Meezan Bank Card Discounts on Restaurants
Meezan Bank card discounts on restaurants come from partnerships with dining brands in Pakistan. Offers usually apply only at listed outlets and for a set time. Check the bank’s website or mobile app for the latest restaurant deals.
Restaurant deals change often. A deal that worked last month may end this week. Because of this, never guess.
Here is how to use dining discounts well:
- Open the Meezan Bank app or website before you eat out.
- Find the restaurant on the current offers page.
- Read the fine print, such as days, cities, and card type.
- Show or use the right card when you pay.
Tip: Ask the cashier to confirm the discount before you order. That saves a bad surprise at the bill.
Meezan Bank World Debit Card Discounts List
The Meezan Bank World Debit Card Discounts List shows partner stores, restaurants, and services that give card savings. The list changes often. Find the newest version on Meezan Bank’s official website, mobile app, or branch.
This article does not copy the full list on purpose. Old lists spread quickly, and they can mislead you. A deal may end, or a store may change its terms.
Instead, use these steps:
- Visit the official Meezan Bank site and search “card offers.”
- Filter by your city and card type.
- Save the page, or screenshot the offer with the date.
That way, you always see real, current savings.
Meezan Bank Discounts List
The Meezan Bank discounts list covers offers across dining, shopping, travel, and more. These deals depend on card type, city, and time frame. Always view the live list on the bank’s official channels.
Discounts can feel like free money. Still, they should not drive your whole banking choice. A 10% discount on one meal does not beat a hidden fee on every trip.
So weigh the two together. Ask yourself:
- Will I really use these partner brands?
- Do the fees cancel out the savings?
- Does the card work well abroad?
If the answer is yes, the discounts become a nice bonus.
Meezan Bank Discounts List PDF
You can often find the Meezan Bank discounts list as a PDF on the bank’s official website under card offers or promotions. Download only from the official site. Third-party PDFs may be outdated or unsafe.
Searching for a PDF is smart. It is easy to save and read offline. Yet old PDFs are common online, and some sites post fake files.
Follow this safe path:
- Go to the official Meezan Bank website.
- Look for “Offers,” “Promotions,” or “Debit Card.”
- Check the date on the PDF.
- If the page has no PDF, call the helpline or visit a branch.
Never share your card number, PIN, or OTP to get a list.
What Is the Best Bank to Use for International Travel?
The best bank for international travel combines no foreign transaction fees, free or refunded ATM use, strong fraud protection, and a widely accepted card network. For most U.S. travelers, Charles Schwab Bank is a top debit choice, while Capital One is popular for credit cards.
No single bank wins for everyone. However, a few features matter most. Look for these:
- No foreign transaction fees: This saves about 3% on each purchase.
- ATM fee refunds: Some banks, like Schwab and Fidelity, refund ATM charges worldwide.
- Strong app tools: You should be able to lock and unlock your card fast.
- Visa or Mastercard: These networks work in most countries.
The table below gives a quick view. Verify current terms before you apply.
| Option | Best For | Key Perk |
|---|---|---|
| Charles Schwab Bank | Debit and ATM use | ATM fee rebates worldwide |
| Fidelity Cash Management | Debit and ATM use | No foreign transaction fees, ATM reimbursements |
| Capital One credit cards | Everyday spending | No foreign transaction fees on many cards |
| Wise | Multi-currency use | Real exchange rate, small fees |
Check each provider’s website for current rules, fees, and eligibility.
Which Bank Account Is Best for International Travel?
The best bank account for international travel is a checking account that has no foreign transaction fees and refunds ATM charges. A multi-currency account can also help. Pair it with a no-fee credit card for safer, cheaper spending abroad.
A checking account with a debit card is the easiest tool for cash. Meanwhile, a travel-friendly credit card works well for hotels and car rentals. Credit cards also give stronger fraud protection in many cases.
Some travelers add a multi-currency account, such as Wise. It lets you hold and spend several currencies. Therefore, you avoid some conversion costs.
Keep two accounts if you can. One acts as your main account. The other holds a small travel balance. If one card fails, the other still works.
Which Bank Account Is Best for Overseas Travel?
For overseas travel, the best bank account has low or no foreign fees, easy ATM access, and good mobile app control. Choose one with fraud alerts and 24/7 support, since time zones can make help hard to reach.
Overseas trips bring special risks. Time zones make phone calls tricky. Also, an ATM in a small town may not accept your card.
So pick an account with these tools:
- A 24/7 customer chat or toll-free number that works abroad
- Instant card lock and unlock in the app
- Real-time spending alerts
- Fast card replacement
Furthermore, consider travel insurance. Some cards include trip delay or rental car coverage. Read the terms, and do not assume every card has them.
Which Pakistani Bank Is Best for International Transactions?
Several Pakistani banks handle international transactions well, including Meezan Bank, UBL, HBL, and Bank Alfalah. The best one depends on your fees, limits, and perks. Compare each bank’s foreign currency charges and card limits before you decide.
No official ranking crowns one winner. Instead, test banks against your needs.
- Frequent flyers: Look for lounge access and travel insurance.
- Online shoppers: Check if international e-commerce is enabled.
- Students abroad: Ask about monthly limits and transfer options.
- Islamic banking preference: Meezan Bank is a leading Islamic option.
Remember, SBP rules affect every bank. So limits may look similar across banks. What changes is service quality, fees, and app tools.
Call the helpline and ask direct questions. A clear answer is a good sign.
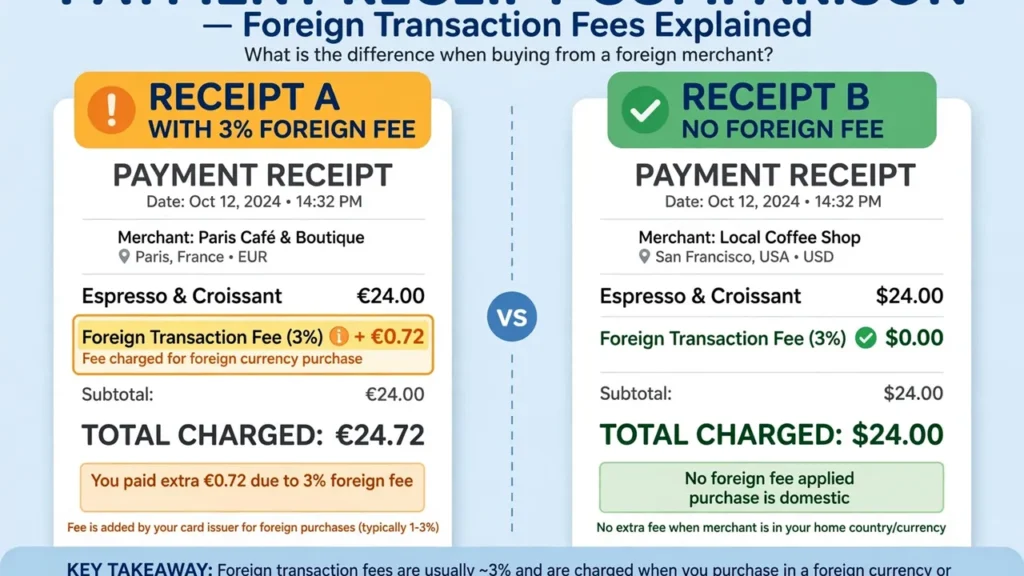
How Do I Avoid a 3% Foreign Transaction Fee?
To avoid a 3% foreign transaction fee, use a card that charges none, such as many travel credit cards or Schwab and Fidelity debit options. Also, always pay in local currency, and decline dynamic currency conversion at checkout.
That fee often hides inside your statement. Card networks and banks add it each time you spend abroad. Over a two-week trip, it can add up fast.
Try these five fixes:
- Get a no-fee card before you leave.
- Pay in local currency. If a terminal asks “USD or euros?”, choose euros.
- Skip airport exchange kiosks. Their rates are often poor.
- Withdraw larger amounts less often, if the ATM fee is flat.
- Use bank ATMs instead of standalone machines.
For example, a $2,000 trip at 3% costs $60 in extra fees. A no-fee card keeps that money in your pocket.
Which Bank Does Elon Musk Use?
Elon Musk’s personal banking details are not public, so no reliable source confirms which bank he uses. Rich public figures often use private banking services. Everyday travelers do not need that level of service to travel well.
It is natural to wonder. Yet guessing leads to false claims. Reliable reports on personal accounts are rare, so do not trust posts that name a single bank.
What matters more is your own setup. You do not need private banking to travel smart. A no-fee card, an ATM rebate account, and a backup card work great.
So skip the celebrity guesses. Focus on fees, access, and safety instead.
Is There a Free International Bank Account Available?
Yes, some accounts have no monthly fee and work abroad, such as Charles Schwab Bank checking and Fidelity Cash Management. Multi-currency accounts like Wise are free to open, but other fees may apply. Always read the fee schedule.
“Free” often means “no monthly fee.” That is not the same as “no cost at all.” Watch for these extras:
- Currency conversion markups
- ATM operator fees
- Card replacement charges
- Wire transfer fees
In short, a free account helps, but only if the rest of the fees stay low. Read the terms. Then compare two or three options side by side.
What Is the Best Way to Spend Money While Traveling Abroad?
The best way to spend money abroad is a mix: a no-fee credit card for most purchases, a debit card for ATM cash, and a small amount of local cash for markets and tips. Always pay in local currency.
This simple mix covers almost every scene. Cards provide safety and good exchange rates. Cash covers the small stuff.
Here is a smart daily plan:
- Morning: Use cash for coffee at a small cafe.
- Afternoon: Pay for museum tickets with a card.
- Evening: Use a credit card for dinner.
Also, split your money. Keep one card in your bag and one in your hotel safe. If you lose one, the other keeps you going.
Finally, skip travelers’checks. Few places take them today.
Which Bank Is the Best for International Transactions?
The best bank for international transactions offers low conversion fees, wide card acceptance, and strong fraud tools. In the U.S., Schwab, Fidelity, and Capital One lead many lists. Wise suits people who send money across borders often.
International transactions include more than travel. They cover online shopping, tuition payments, and sending money home.
So think about your goal:
- Travel spending: Pick a no-fee card and ATM rebates.
- Sending money abroad: Compare transfer apps and bank wires.
- Online shopping: Make sure foreign purchases are allowed.
In each case, the real exchange rate matters most. A “no fee” offer can still hide a poor rate. Compare the rate to the mid-market rate on a trusted currency site.
Which International Travel Card Has No Fees?
No travel card is truly fee-free, but many have no foreign transaction fee. Some also skip annual fees. Look at ATM charges, currency conversion, and replacement costs, because those can still apply.
Be careful with the phrase “no fees.” It rarely tells the full story. A card with no foreign transaction fee may still charge an annual fee. Likewise, a debit card may refund ATM costs but charge for replacements.
Check this short list before you apply:
- Foreign transaction fee
- Annual fee
- ATM fees and refunds
- Currency conversion rate
- Replacement card cost
Then choose the card with the lowest total cost for your style of travel.
Which Bank Is Good for International Use?
A bank is good for international use if its card works in many countries, charges low fees, and supports travelers with strong apps and customer service. Large banks on Visa or Mastercard networks usually meet these needs.
Big networks make a big difference. Visa and Mastercard work in most of the world. Smaller card types may not.
Also, test the bank before you leave:
- Try the app’s card lock feature.
- Save the bank’s overseas phone number.
- Confirm your travel notice, if needed.
A bank that gives you control from your phone is a bank that helps you abroad.
Which Bank Card Is Best for Travel?
The best bank card for travel has no foreign transaction fees, earns useful rewards, and offers protections like trip delay coverage. Many travelers carry one travel credit card and one fee-friendly debit card.
Credit cards often win for travel. They offer purchase protection and fraud help. Many also earn points or miles.
Pick based on how you travel:
| Traveler Type | Best Card Style |
|---|---|
| Occasional vacationer | Simple no-fee credit card |
| Frequent flyer | Airline or travel rewards card |
| Budget backpacker | Debit card with ATM refunds |
| Family trip | Rewards card plus a backup card |
See each issuer’s page for the latest rewards, annual fees, and rules.
Is UBL Better or Meezan?
Neither UBL nor Meezan is better for everyone. UBL is a large commercial bank with wide reach. Meezan is a leading Islamic bank. Compare card fees, limits, perks, and your own banking style before you choose.
The right answer depends on your needs. Here is a simple view:
| Factor | UBL | Meezan Bank |
|---|---|---|
| Banking type | Conventional | Islamic |
| Best for | Travelers wanting a large network | Customers who prefer Shariah-compliant banking |
| What to check | Card fees and limits | Card tier and perks |
Because fees and perks change, compare both banks’ current fee schedules. Also visit a branch if you can. How easy the bank is to work with matters as much as its card.
Is Meezan Bank International?
Meezan Bank is a Pakistani bank, so its branches focus on Pakistan. Its Visa and Mastercard debit cards, however, work internationally at shops and ATMs that accept those networks. Check international use settings before you travel.
So, the bank is not a global chain like some large U.S. or European banks. Even so, its cards ride on global networks. That lets you spend abroad.
Before you go:
- Confirm international use is switched on.
- Ask about daily ATM limits abroad.
- Save the helpline number for emergencies.
Then you can travel with less stress.
Which Pakistani Bank Card Can Be Used Internationally?
Most Pakistani bank cards on Visa or Mastercard can work internationally if the bank has enabled that feature. Banks like Meezan, UBL, HBL, and Bank Alfalah offer such cards. Confirm limits and fees first.
Local-only cards, such as some domestic debit cards, will not work abroad. Look for the Visa or Mastercard logo. Also check for the global acceptance mark.
Follow these steps:
- Check your card for a Visa or Mastercard logo.
- Call your bank to turn on international use.
- Ask about yearly or monthly limits under SBP rules.
- Test the card on a small online purchase.
SBP rules can change, so view the official SBP site for current guidance.
Quick Mistakes Travelers Make (and Easy Fixes)
The most common money mistakes abroad are using airport exchange booths, paying in the wrong currency, and traveling with only one card. Each mistake costs money or causes stress, but each one has a simple fix.
- Mistake: Exchanging cash at the airport. Fix: Use a bank ATM in the city.
- Mistake: Choosing your home currency at checkout. Fix: Always pay in local currency.
- Mistake: Bringing only one card. Fix: Carry two, and store them apart.
Honest drawback: even the best setup can fail. ATMs break,ak and cards get blocked. So always keep a small emergency cash reserve.
FAQs
Do I need to tell my bank before I travel abroad?
Many banks no longer require it, but a travel notice still helps. It can lower the chance of a blocked card. You can usually add one in your bank’s app or by phone.
Also, make sure your phone number is current. That way, fraud alerts reach you quickly.
Is it better to use a credit card or a debit card overseas?
Credit cards are usually better for purchases because they offer stronger fraud protection and rewards. Debit cards work better for ATM cash.
Many travelers use both. Pick a no-foreign-fee credit card and a debit card with ATM refunds.
How much cash should I carry on an international trip?
Carry enough for the first day, such as transport, tips, and small meals. For most trips, that means a modest amount of local currency.
Then withdraw more as needed. Also keep some cash hidden as a backup.
What should I do if my card is lost or stolen abroad?
Lock the card in your app right away, then call your bank to cancel it and request a replacement.
Next, use your backup card. Save your bank’s overseas phone number before you travel so you can reach it quickly.
Is it safe to use ATMs in other countries?
Yes, ATMs inside banks or at airports are generally safer than street machines. Cover the keypad, check for loose card slots, and avoid ATMs in dark areas.
Also, check your account later for strange charges.
Conclusion
Choosing the best bank for international travel comes down to a few clear steps. Here are your three key takeaways:
- Avoid foreign transaction fees. Pick a card that charges none.
- Use a smart mix. Carry a no-fee credit card, a debit card with ATM refunds, and a backup.
- Verify before you go. Fees, limits, and discounts change, so check official bank websites.
A little prep saves real money and keeps your trip smooth. Compare two or three options this week. Then pack your cards, your passport, and your sense of adventure. The world is waiting, and your wallet is ready.
Maya Lin inspires travelers to explore the globe with absolute confidence and independence. Armed with a background in digital media and a decade of independent solo travel experience, she knows exactly how to navigate unfamiliar cities smoothly and safely. For Travelmarse, Maya curates the solo travel and hidden-gem verticals. She reviews charming boutique hotels, designs smart neighborhood walking routes, and shares practical language-learning hacks, giving readers the exact tools they need to travel solo without the stress.